August is often a quiet month in the automotive calendar, a lull between summer shutdowns and the fall launch season. But in 2026, August tells a much bigger story. It is the month when the industry’s pivot to electric vehicles stops being a forecast and starts showing up in production plans and plant-level investment decisions. It is also the month when decisions made years ago, from retooling investments to supply chain reshoring, finally show their hand.
This analysis examines model-level and plant-level production trends for August and year-to-date 2026 to give industry stakeholders, analysts, and enthusiasts a clear picture of where North American auto manufacturing stands and where it is heading. According to available industry data, the picture that emerges is one of an industry in transition, though specific production figures require verification against primary sources. Traditional trucks and SUVs still dominate volume, but EVs are gaining share faster than many predicted, and the geography of production is shifting in ways that carry real economic consequences.
Overall Production Trends: August and YTD 2026
North American vehicle production in 2026 reflects an industry that has largely stabilized after several years of disruption. Total car and truck output for August and the year-to-date period points to a market that is growing modestly, not booming, with the mix of vehicles shifting decisively toward light trucks, crossovers, and electrified powertrains. Readers seeking exact unit volumes and year-over-year percentage changes should consult primary sources such as S&P Global Mobility, Wards Intelligence, and individual automaker production reports, which publish monthly and quarterly figures.
Several factors shape the 2026 picture. Supply chains have improved compared to the worst of the chip shortage years, though semiconductor availability remains a constraint for the most advanced driver-assistance and infotainment systems. Consumer demand has held up better than some economists expected, supported by a strong labor market and pent-up replacement demand from vehicles bought during the pandemic-era shortages. At the same time, higher interest rates have cooled the pace of new vehicle purchases, which keeps production plans disciplined rather than aggressive.
The year-to-date trends confirm what monthly data hints at: trucks and SUVs continue to account for the large majority of North American output, while traditional sedan production remains a niche segment dominated by a handful of models. Electric vehicle production, meanwhile, is the fastest-growing category in the dataset, even as it starts from a smaller base.
Model-Level Production Trends: What Is Moving Off the Lines
At the model level, the August and YTD 2026 trends reveal three clear stories.
First, full-size pickup trucks remain the backbone of North American production. Models like the Ford F-Series, Chevrolet Silverado, and Ram 1500 continue to post the highest volumes of any vehicles built on the continent. These trucks are not just consumer products; they are profit centers for the Detroit Three and a major source of employment across the Midwest and South.
Second, compact and midsize crossovers are the volume leaders in the passenger vehicle space. Models such as the Toyota RAV4, Honda CR-V, and Chevrolet Equinox consistently rank among the top-produced vehicles, reflecting consumer preference for utility, fuel efficiency, and ride height over traditional sedans.
Third, and most significantly, electric models are climbing the production rankings. Tesla remains the highest-volume EV producer in North America, and its Fremont and Austin plants continue to anchor the continent’s electric vehicle output. But Tesla is no longer alone. The Ford Mustang Mach-E, Chevrolet Equinox EV, and a growing list of battery-electric crossovers and SUVs are adding meaningful volume. Hybrid production is also expanding, particularly for models like the Toyota RAV4 Hybrid and Ford F-150 Hybrid, as automakers hedge their bets between full electrification and continued internal combustion demand.
The model-level trends also show a quiet retreat from certain segments. Several traditional sedans and small cars have seen production wind down or end entirely as automakers reallocate capacity to crossovers and EVs. This is not a new trend, but 2026 is the year it becomes nearly complete across most mainstream brands.
Plant-Level Production Breakdown: Where the Metal Is Being Stamped
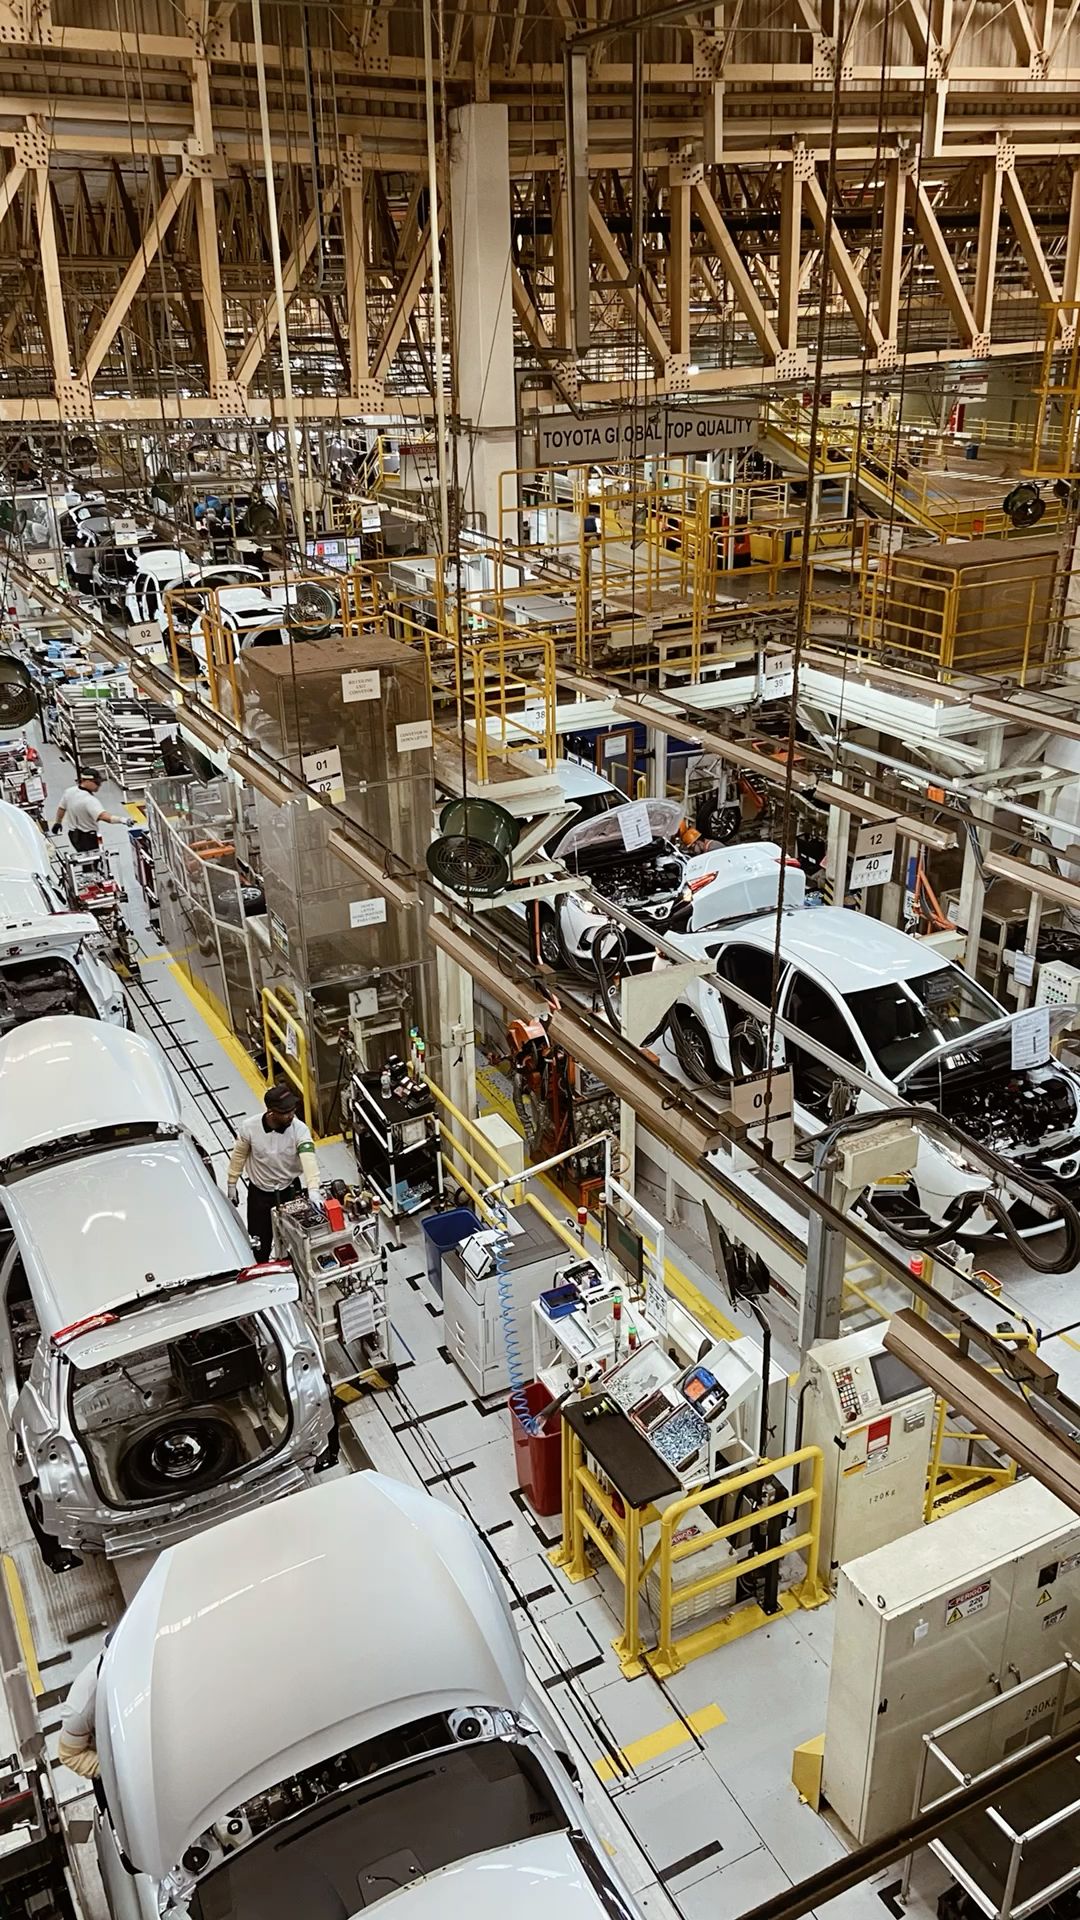
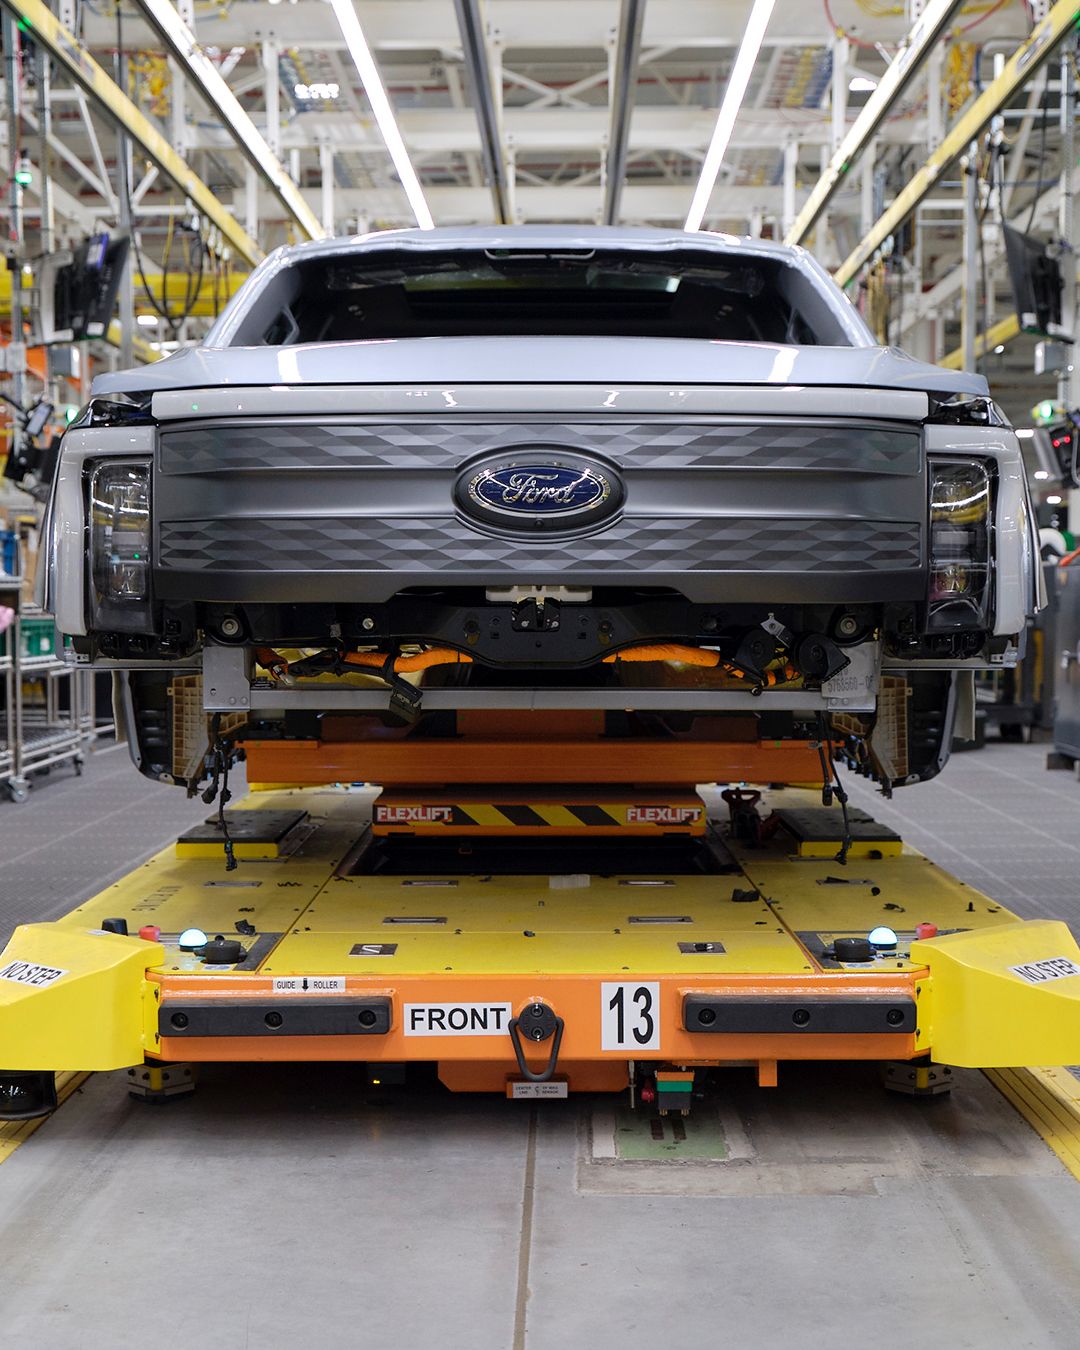
The plant-level view is where the EV transition becomes most visible. Assembly plants across the United States, Canada, and Mexico are in different stages of retooling, and their output reflects that. The table below summarizes the major plants referenced in this analysis and the trends shaping their production.
| Plant | Location | Models | Powertrain | Notable trend |
|---|---|---|---|---|
| Dearborn Truck Plant | Dearborn, Michigan | Ford F-150 | ICE, hybrid | High-volume F-Series production |
| Kentucky Truck Plant | Louisville, Kentucky | Ford Super Duty, Expedition | ICE | Sustained heavy-duty output |
| Flint Assembly | Flint, Michigan | Chevrolet Silverado HD, GMC Sierra HD | ICE | Key heavy-duty truck site |
| Fort Wayne Assembly | Roanoke, Indiana | Chevrolet Silverado, GMC Sierra | ICE | Core light-duty truck production |
| Factory ZERO | Detroit, Michigan | Multiple GM EVs | BEV | Converted for EV production |
| Spring Hill Assembly | Spring Hill, Tennessee | Cadillac Lyriq and other GM models | BEV, ICE | Mixed EV and ICE output |
| Rouge Electric Vehicle Center | Dearborn, Michigan | Ford F-150 Lightning | BEV | Dedicated EV truck plant |
| Kansas City Assembly | Claycomo, Missouri | Ford E-Transit, Transit | BEV, ICE | Commercial van production |
| Fremont Factory | Fremont, California | Tesla Model 3, Model Y | BEV | Long-running Tesla site |
| Gigafactory Texas | Austin, Texas | Tesla Model Y, Cybertruck | BEV | Highly automated EV production |
| Cambridge and Woodstock | Ontario, Canada | Toyota RAV4 and other models | ICE, hybrid | Growing hybrid share |
| Alliston | Ontario, Canada | Honda CR-V, Civic | ICE, hybrid | Core Canadian passenger output |
| Windsor Assembly | Windsor, Ontario | Stellantis minivans and EVs | ICE, BEV | Retooled for electrification |
| Ramos Arizpe | Coahuila, Mexico | GM crossovers and EVs | ICE, BEV | Expanding EV role |
| Cuautitlan | Mexico State, Mexico | Ford Mustang Mach-E | BEV | Export-oriented EV production |
The pattern across these plants is consistent. Truck and SUV plants continue to run at high utilization, EV-dedicated plants are ramping, and mixed-use plants are balancing internal combustion and electrified output as consumer demand evolves. The plants receiving the largest recent investment are overwhelmingly those tied to electrification and battery production.
Regional Shifts and Economic Impact
The geographic distribution of North American auto production is shifting, and the economic implications are significant.
The United States remains the largest producer by volume, with the Midwest and South accounting for the majority of output. Southern states like Tennessee, Kentucky, Alabama, Georgia, and Texas have attracted billions in new investment, particularly for EV and battery production. This has created new manufacturing jobs but also intensified competition among states for automaker investment.
Canada’s auto industry is concentrated in Ontario and faces pressure from both the EV transition and broader economic forces. Canadian plants have secured significant EV-related investment, including battery manufacturing, but the country’s share of North American production has been slowly declining for years. The transition to EVs represents both an opportunity and a risk for Canadian autoworkers.
Mexico has emerged as a major beneficiary of the shift, with automakers investing heavily in EV and component production south of the border. Mexico’s role in the North American supply chain is expanding, particularly for battery components and electric vehicle assembly. This growth brings economic benefits but also raises questions about labor standards and supply chain resilience.
Challenges and Opportunities Ahead
The remainder of 2026 will be shaped by several forces.
Semiconductor supply remains a wild card. While the worst of the shortage is over, advanced chips for EVs and autonomous driving features are still in tight supply. Any disruption could ripple through production schedules.
Labor is another factor. Contract negotiations and workforce transitions as plants retool for EVs will be closely watched. The shift to electric vehicles requires different skills and, in some cases, fewer workers, which creates tension between automakers and unions.
On the opportunity side, consumer acceptance of EVs continues to grow, and new models are arriving at lower price points. Battery costs are declining, and charging infrastructure is expanding. These trends suggest that EV production will continue to gain share through the rest of 2026 and beyond.
Conclusion: What the Trends Tell Us
The August and year-to-date 2026 production trends point to an industry in the middle of a historic transition. Trucks and SUVs still generate the bulk of volume and profit, and they will for years to come. But the growth is in electrified vehicles, and the plants building them are the ones receiving the investment.
For industry stakeholders, the message is clear: the shift to EVs is no longer a future scenario. It is happening now, plant by plant, model by model. The most useful next step for analysts is to pair this qualitative view with hard figures from primary data providers, tracking monthly output by plant and model to confirm which regions and powertrains are gaining share fastest. The trends from 2026 are not just a snapshot. They are a preview.